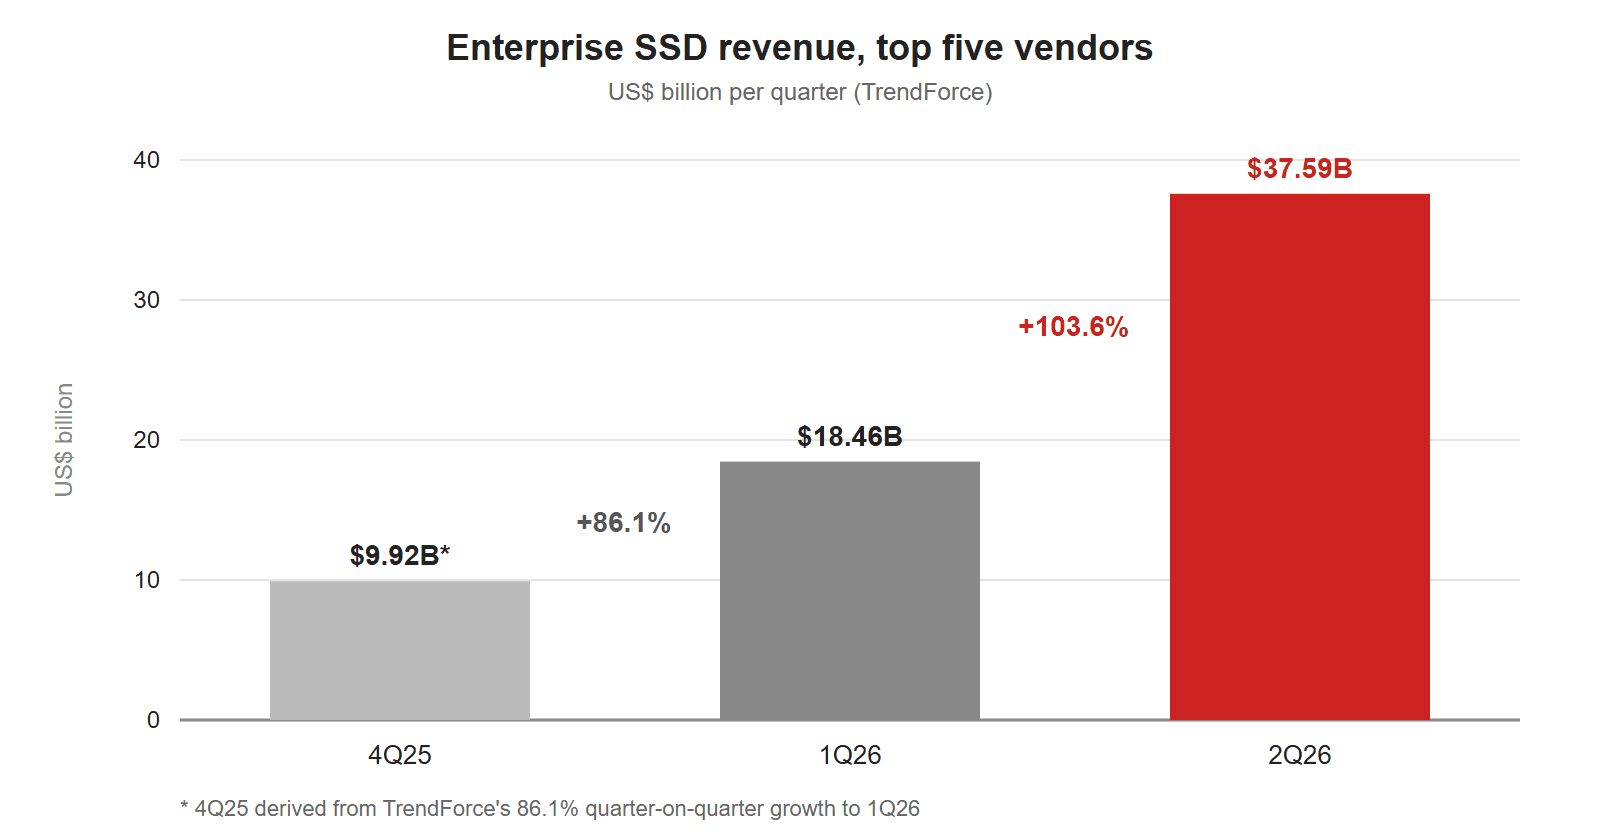
The NAND and SSD shortage of 2026 is a supply decision: memory makers moved fab lines to DRAM and HBM, and enterprise flash pays for it. Revenue of the top five enterprise SSD vendors doubled to $37.59 billion in 2Q26, and on 30 September TrendForce forecast NAND contract prices up another 15 to 20% in 4Q26, with enterprise SSD increases speeding up. If you are buying storage for 2027, lock volumes and terms now and plan for tight supply until the second half of 2027.
Everyone covering the data center memory shortage 2026 is telling the same demand-side story: AI needs more HBM, so prices spike, so buy your DRAM now. I’ve spent enough time around clean rooms and beamline schedules to tell you that story is incomplete, maybe even backwards. The bigger driver is a supply-triage decision playing out quietly inside the world’s memory fabs, and it has more to do with margin math than with any shortage of silicon.
The uncomfortable part is that manufacturers are not simply failing to build enough memory. They are cannibalizing NAND flash production, the chips inside enterprise SSDs, by moving parts of their production lines over to DRAM, where the AI-accelerator margins are. The result is a flash shortage that is only partly about flash demand. Enterprise flash storage is collateral damage from where the semiconductor industry chose to point its capacity, and hyperscalers are left holding the bag.
The 2026 Data Center Memory Shortage Isn’t What You Think
The public numbers tell you how bad it already feels. When Micron reported its fiscal second quarter on 18 March 2026, revenue had nearly tripled from a year earlier to $23.86 billion, and the company pointed to a strong demand environment and “tight industry supply” (Micron results release). That’s the framing most coverage stops at: too much demand, not enough chips.
But “not enough chips” misses where the wafers are actually going. HBM demand is projected to grow by more than 70% year-over-year in 2026, according to TrendForce’s “Memory Wall Bottleneck” analysis. Fabs can’t add clean-room space fast enough to match that curve, so they are reallocating what they already have. In February TrendForce reported that memory makers were “proactively reallocating parts of their production lines to DRAM” even though NAND orders far exceeded output, a shift it said further limits NAND capacity growth (TrendForce, February 2026). The shortage comes from a decision about which memory to build, and enterprise flash lost the vote.
Inside the Wafer Math: Why HBM Wins and NAND Loses
The structural root of this bottleneck is a brutal piece of silicon economics: producing a given number of HBM bits takes about three times the wafer area of standard DDR5. That is Micron’s own figure, and at Hot Chips in August its HBM design fellow said the gap is growing with every generation (Tom’s Hardware). Demand for those stacks is set by AI packages that place several HBM stacks beside each GPU, the same pressure pushing packages onto ever larger substrates, as our report on Intel’s glass core substrate explains. Think of a fab’s clean room the way I think of beamtime at CERN. There are only so many hours on the accelerator, and every experiment competes for the same slots regardless of how “important” it is. When one experiment pays ten times more per hour of beamtime, the schedule fills up with that experiment, and everything else gets bumped. HBM is that experiment right now.
That’s the mechanism nobody puts in the headline: fabs are moving clean-room capacity toward DRAM and HBM output, because HBM’s margins simply outrun what commodity flash can command. TrendForce frames this as the industry’s “memory wall,” and the framing is apt: a wafer start can only go to one product. Every wafer start moved toward DRAM and HBM is one that could have made the flash inside your storage array. Stacking cache memory under a logic die costs almost nothing thermally, as our piece on 3D chip stacking’s thermal limit shows; for HBM, the cost that matters here is wafer area. This is the same physical-capacity logic driving the broader wafer-scale inference shift I’ve written about before: silicon area is the scarcest resource in this entire AI buildout, scarcer than power, scarcer than floor space.
Get the next one by email
Power, cooling, chips and the rules that shape them. No spam, unsubscribe any time.
Enterprise SSDs Become Collateral Damage
Data centers now face a storage bottleneck made worse by a chip they don’t even use for storage. Revenue for the top five enterprise SSD vendors rose 86.1% quarter-on-quarter to $18.46 billion in 1Q26, then doubled again to $37.59 billion in 2Q26, according to TrendForce’s rankings (June, September). Part of that is real demand: AI agent services have cloud providers buying high-capacity drives and moving from PCIe 4.0 to PCIe 5.0. But price is doing much of the work. Enterprise SSD contract prices rose about 80% in the first quarter alone, as supplier inventories fell to historic lows and output lagged far behind orders. That is what demand looks like when supply can’t follow: in July TrendForce said NAND makers would rely mainly on process upgrades this year, because fab space is constrained and manufacturers “continue prioritizing DRAM capacity expansion” (TrendForce, July 2026).
I’d argue this is the most underreported dynamic in the entire 2026 buildout. Every other AI infrastructure bottleneck I’ve covered, from grid power to cooling and interconnect, is at least caused by AI workloads directly stressing the resource in question. This one is only half that. AI demand for flash is real, but enterprise storage is getting squeezed hardest because the fabs that make it decided a different chip, for a different purpose, was worth more per wafer. It is a triage decision with a real casualty, and the casualty sits in your storage tier rather than your GPU rack.
⚡ PHOTON’S TAKE
Stop calling this an HBM story. HBM is doing exactly what its economics tell it to do: chase the margin, every time. The real headline is that the memory industry just ran a silent triage and enterprise flash lost. Nobody with an AI accelerator order sheet asked for a 30TB SSD shortage; the fabs created one anyway, by pointing spare capacity at the highest-margin product. If you’re planning storage capacity past 2026 on the assumption that flash follows its own supply curve, you’re planning against a curve that no longer exists.
The Data Center Memory Shortage Has No Quick Fix
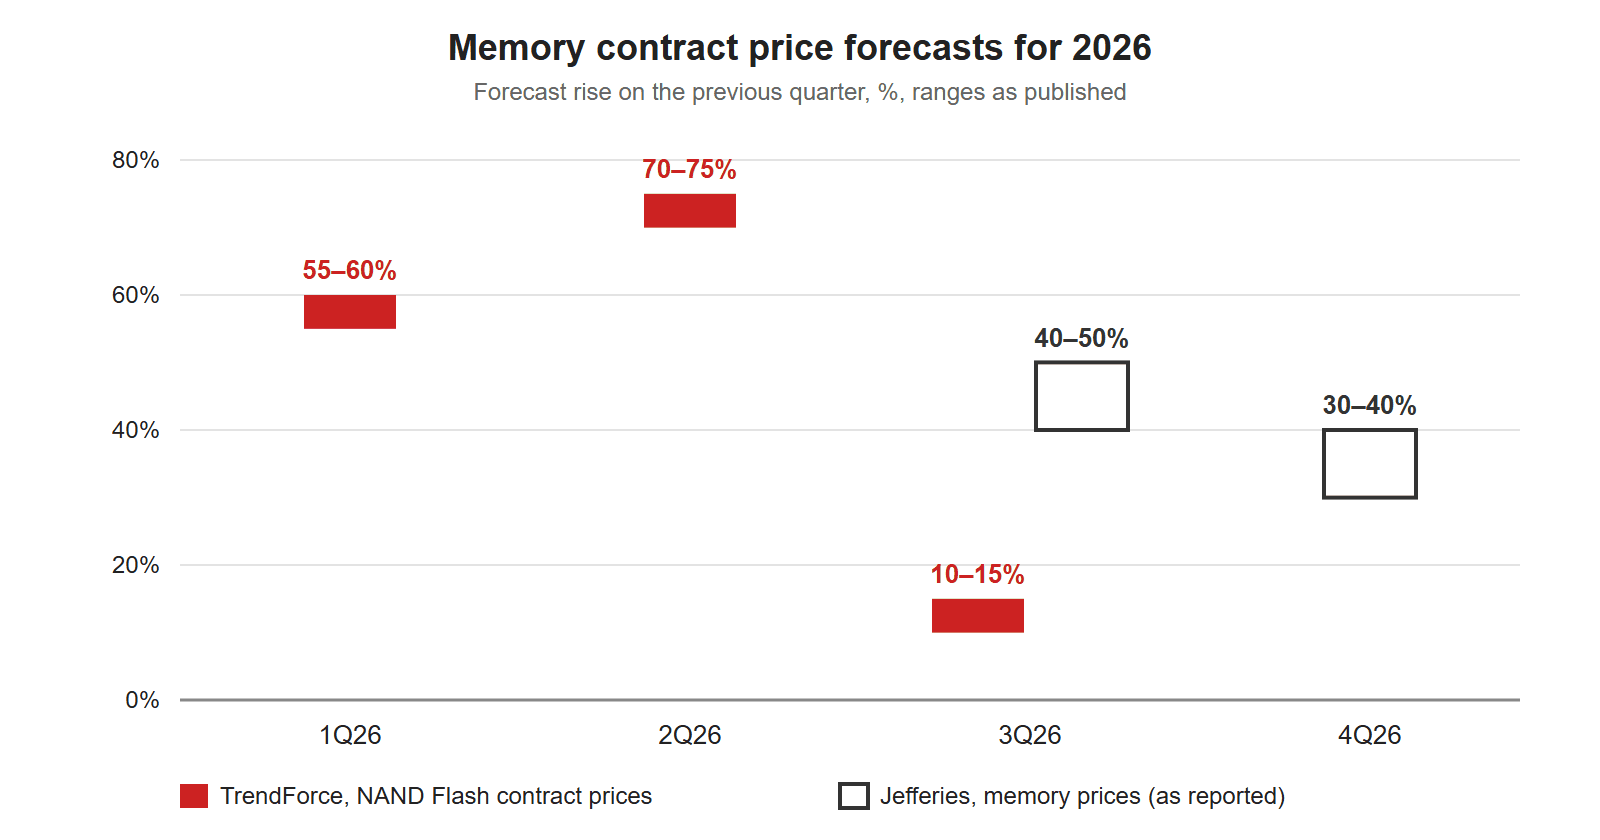
How long does it last? The forecasts disagree more than the headlines suggest. Jefferies was reported in late June as expecting memory prices to rise another 40 to 50% in Q3 2026 and 30 to 40% in Q4, with little relief before 2028 (Wccftech). TrendForce’s own survey is far calmer: NAND flash contract prices up 10 to 15% in 3Q26, after forecast rises of 55 to 60% and 70 to 75% in the first two quarters (TrendForce, July 2026). Its 30 September forecast turned back up: NAND contract prices rise 15 to 20% in 4Q26, and enterprise SSD is the only memory category whose increases are expected to accelerate, because most new supply is already committed and suppliers allocate capacity by profitability (TrendForce, 30 September 2026). In July it expected NAND to stay 4 to 5% undersupplied through 2026, with supply overtaking demand only in the second half of 2027 (TrendForce, 21 July 2026). Either way, this is a multi-year repricing of an entire category rather than a blip you wait out, layered on top of the $1 trillion data center boom already straining power and grid capacity. Fabs will eventually build new clean-room capacity dedicated to flash again, but new fabs take years, not quarters, and nobody breaks ground for a product with HBM-level margins sitting right next door.
My honest read: this triage won’t reverse until either HBM demand growth cools or hyperscalers start designing storage tiers around scarcer, denser flash rather than assuming volume will always be there. Until then, treat enterprise SSD supply the way you’d treat beamtime on an oversubscribed accelerator: book early, expect delays, and don’t assume next quarter looks like this one. The AI memory shortage is really about everything AI’s favorite chip pushed out of the way to get made.
Updated October 2026: added TrendForce’s 30 September forecast for 4Q26 NAND and enterprise SSD contract prices. Updated 25 September 2026: the enterprise SSD revenue figures, the price forecasts and the HBM wafer ratio were corrected against primary sources, and both charts were redrawn from TrendForce data.
Cite this article
Turner, A. (2026, July 15). Data Center SSD Shortage 2026: Why NAND Lost to DRAM. ScienceShot. https://scienceshot.com/post/data-center-memory-shortage-2026
Turner, Alex. “Data Center SSD Shortage 2026: Why NAND Lost to DRAM.” ScienceShot, 15 July 2026, scienceshot.com/post/data-center-memory-shortage-2026.
Turner, Alex. “Data Center SSD Shortage 2026: Why NAND Lost to DRAM.” ScienceShot, July 15, 2026. https://scienceshot.com/post/data-center-memory-shortage-2026.
@online{scienceshot-data-center-memory-shortage-2026,
  author       = {Turner, Alex},
  title        = {{Data Center SSD Shortage 2026: Why NAND Lost to DRAM}},
  organization = {ScienceShot},
  date         = {2026-07-15},
  year         = {2026},
  url          = {https://scienceshot.com/post/data-center-memory-shortage-2026}
}
https://scienceshot.com/post/data-center-memory-shortage-2026
Get the weekly brief
Sourced analysis of data-centre engineering and regulation, every Monday. No spam, unsubscribe any time.