Key takeaways
- On 15 October 2026 our pipeline tracker listed 468 data-centre projects in Europe. Of these, 295 (63%) are outside the seven metros where the industry has clustered: Frankfurt, London, Amsterdam, Paris, Dublin, Milan and Madrid.
- Finland has 41 tracked projects, more than any single hub metro. Norway, Sweden and Denmark together have 41, the UK outside London 36, Spain outside Madrid 30 and France outside Paris 29.
- Projects outside the hubs are at an earlier stage: 40% have only been announced, against 11% in the five FLAP-D metros. Still, 64 of them are under construction or structurally complete, against 33 in FLAP-D.
- These are counts of projects. Capacity is published on different bases (IT load, campus power, grid connection), so we never add megawatts together.
- To judge a market, read the stage of each project in the pipeline tracker, then the grid rules for the same market in our grid connection tracker.
Most of the data-centre projects in our European tracker are outside the big hubs. On 15 October 2026 the ScienceShot pipeline tracker listed 468 projects, and 295 of them were outside the seven hub metros. Finland alone has 41, more than London (37) or Frankfurt (35). The difference is in the stage. Of the 295 projects outside the hubs, 117 (40%) have only been announced: the developer has published a plan, and we found no permit and no start of works. In the five FLAP-D metros (Frankfurt, London, Amsterdam, Paris and Dublin), that share is 11%.
This walkthrough reads the tracker by area and stage, then shows how to check one market yourself. Every count comes from the ScienceShot data-centre pipeline, which records each project’s latest public milestone and the source for it.
Where the projects are, area by area
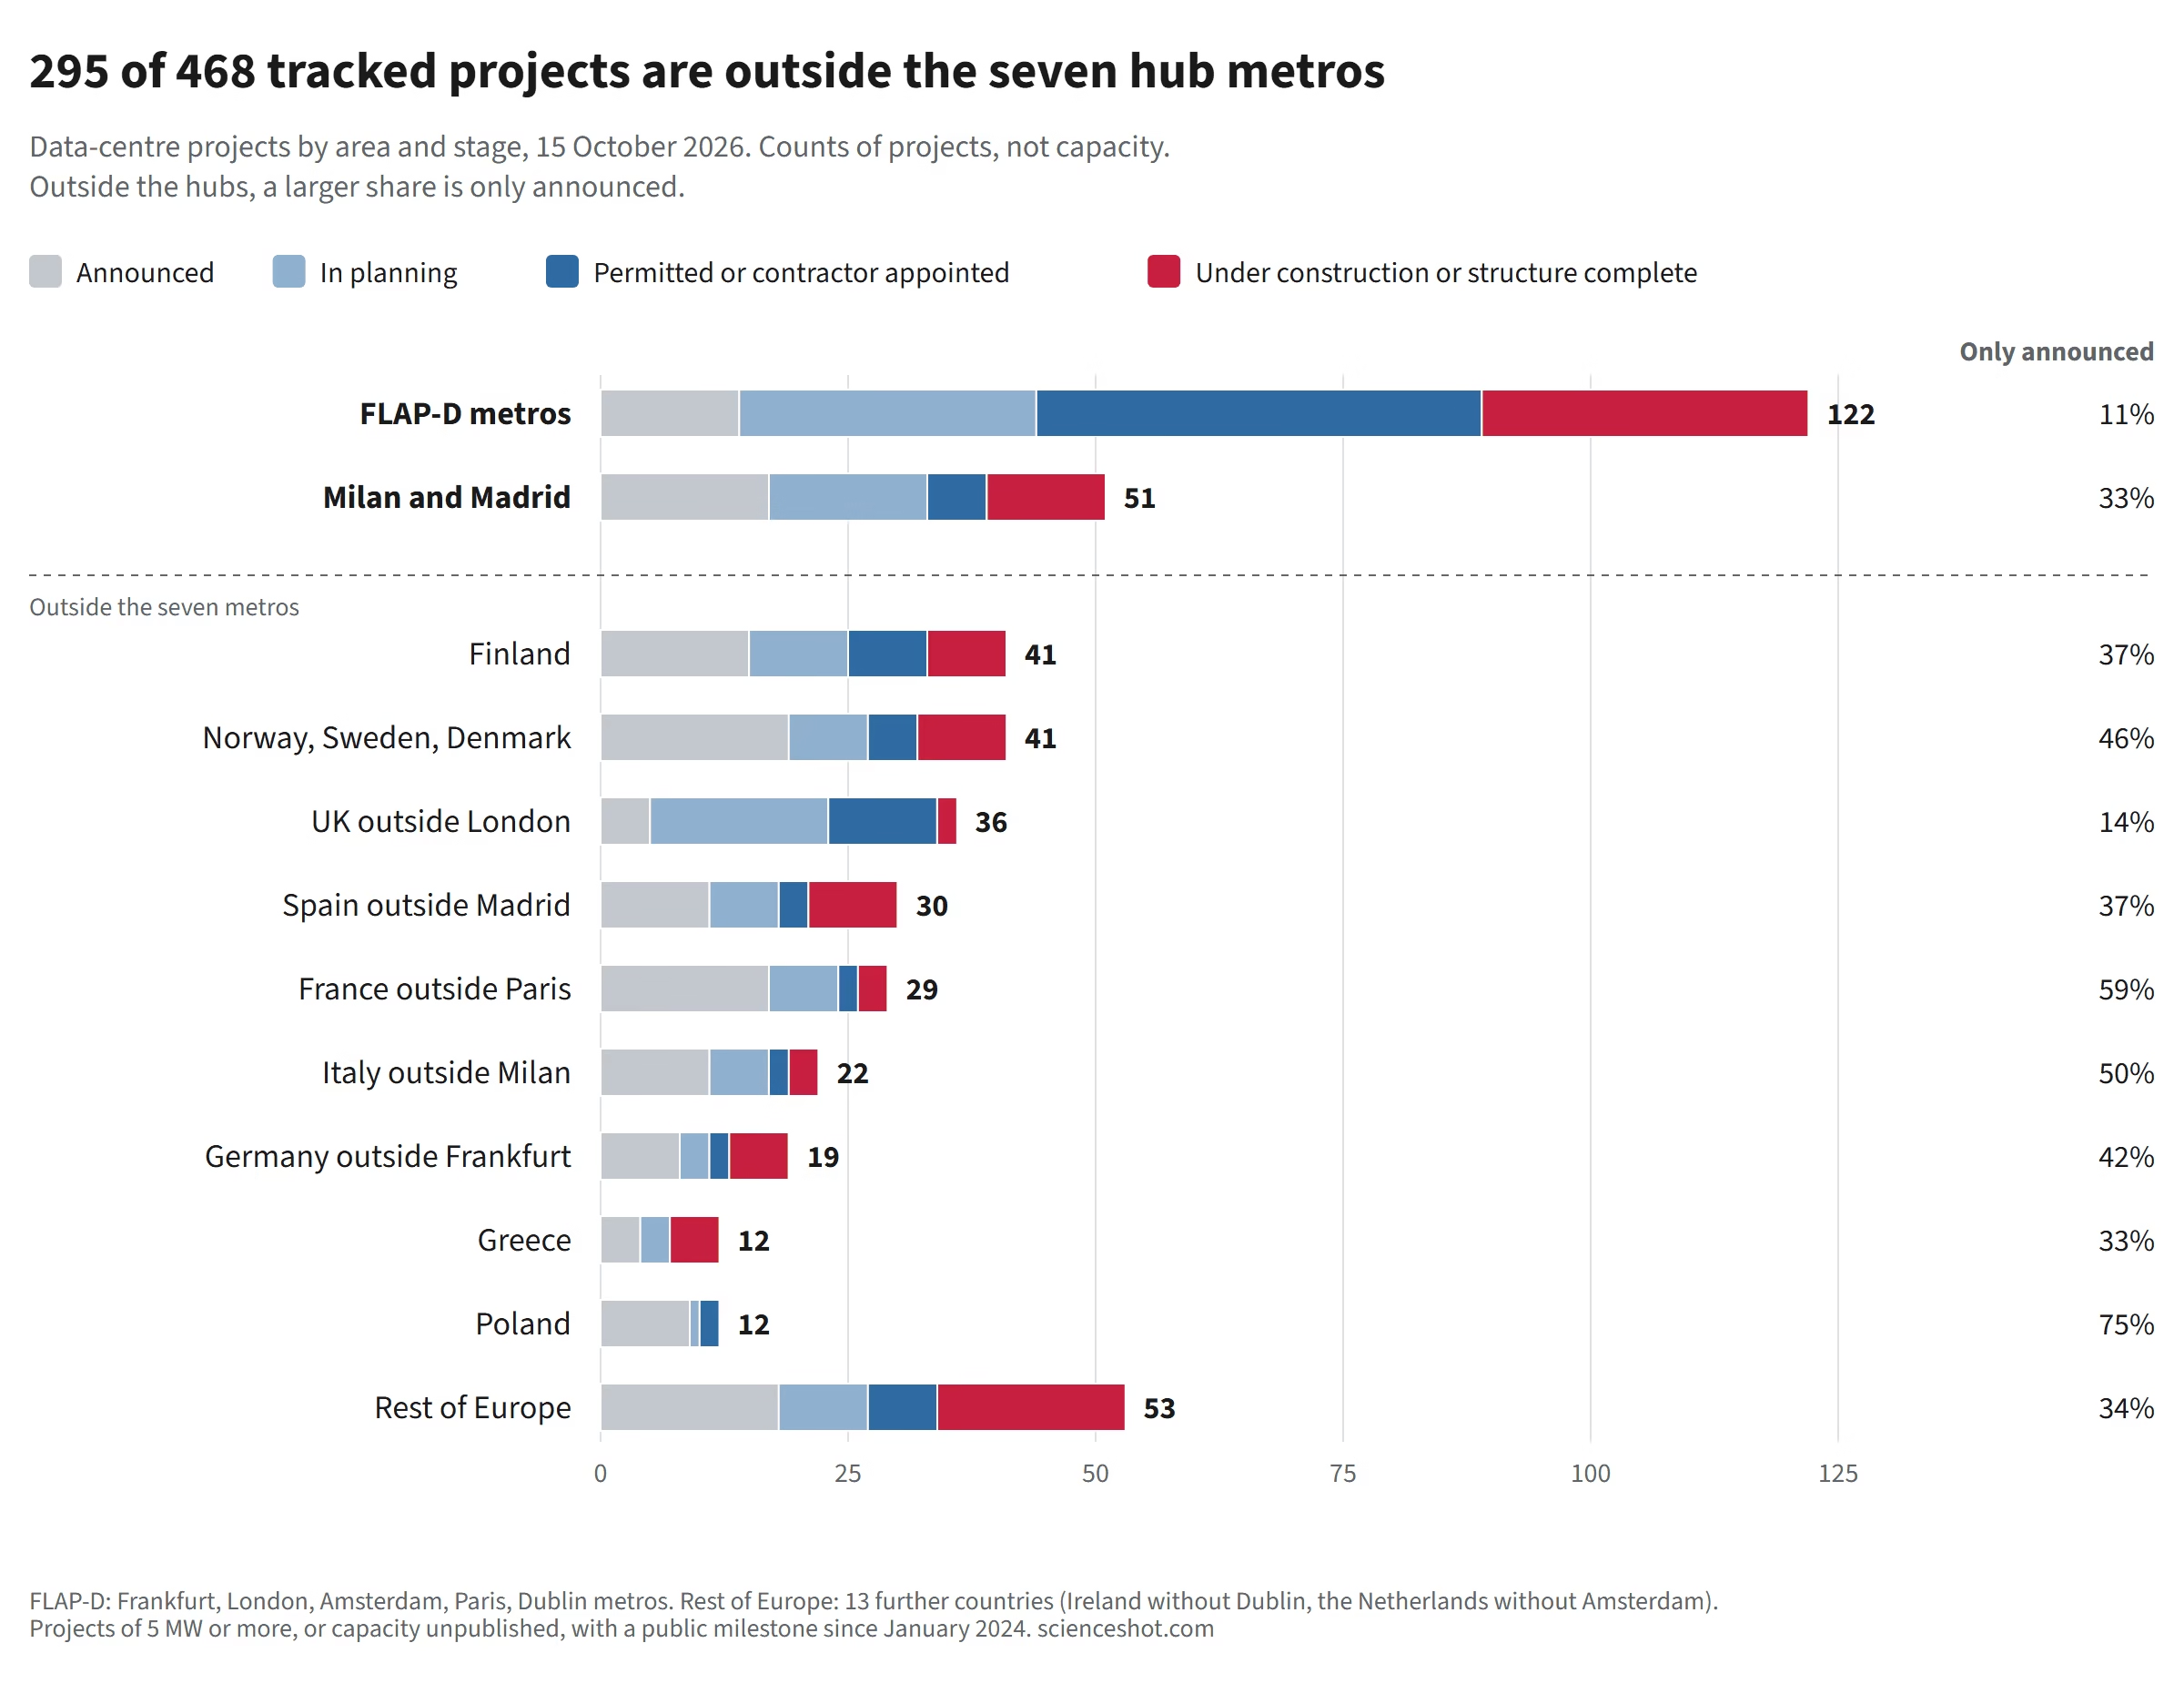
The chart groups the tracker’s 468 projects by area and stage. The two hub groups sit at the top; everything below the line is outside the seven metros.
| Area | Projects | Announced | In planning | Permitted or contractor appointed | Under construction or structure complete |
|---|---|---|---|---|---|
| FLAP-D metros | 122 | 14 | 30 | 45 | 33 |
| Milan and Madrid | 51 | 17 | 16 | 6 | 12 |
| Finland | 41 | 15 | 10 | 8 | 8 |
| Norway, Sweden, Denmark | 41 | 19 | 8 | 5 | 9 |
| UK outside London | 36 | 5 | 18 | 11 | 2 |
| Spain outside Madrid | 30 | 11 | 7 | 3 | 9 |
| France outside Paris | 29 | 17 | 7 | 2 | 3 |
| Italy outside Milan | 22 | 11 | 6 | 2 | 3 |
| Germany outside Frankfurt | 19 | 8 | 3 | 2 | 6 |
| Greece | 12 | 4 | 3 | 0 | 5 |
| Poland | 12 | 9 | 1 | 2 | 0 |
| Rest of Europe | 53 | 18 | 9 | 7 | 19 |
Rest of Europe groups 13 smaller markets, among them Ireland outside Dublin and the Netherlands outside Amsterdam. Milan and Madrid, the two secondary hubs, hold 51 projects between them, so 346 projects (74%) are outside FLAP-D.
The UK outside London is the exception to the early-stage pattern. Only 5 of its 36 projects are merely announced, but only 2 are under construction; 29 are in planning or hold a permit. Poland is at the other end: 9 of its 12 projects are announced, and none is under construction yet. In Germany outside Frankfurt, 6 of 19 projects are under construction or structurally complete.
What a new project meets in the hubs
The tracker records milestones and their sources; it cannot say why a developer chose a site. Our other trackers do show what a new project runs into in the hubs. All of it is in the grid connection tracker, and the Amsterdam rule is in our register of refusals.
- In Frankfurt, the distributor no longer serves requests of 3.5 MW and more in order of arrival. It shares out the capacity at each grid node once a year, and it expects restrictions until the mid-2030s.
- In the Dublin region, the transmission operator says a data-centre application in a constrained area cannot be progressed, and the region is constrained.
- Amsterdam’s zoning plan bars, in principle, new or expanded data centres above 2,000 m² and 5 MVA (megavolt-amperes, the unit grid operators use for the size of a connection).
- In west London, the transmission reinforcement that would relieve the grid constraint is due in 2037.
The regions have limits of their own. Since October 2026, Danish rules put data centres in the last of four priority categories for a new grid connection, unless they serve a critical societal function. In central and southern Stockholm, the Swedish transmission operator says all its capacity for withdrawals is currently allocated. Our article on grid connection waits covers both.
Get the next one by email
Power, cooling, chips and the rules that shape them. No spam, unsubscribe any time.
Power stations and paper mills
Eleven projects outside the hubs give a power-station site as their location, most of them former plants. Seven of the 11 have only been announced. Two are under construction: Schwarz Digits at a former power plant site in Lübbenau, Brandenburg, and QTS at the former Blyth Power Station in Cambois, Northumberland. At Drax’s Selby power station, the planning application for the first phase was still being prepared when we last checked.
At least three more projects sit on paper-mill sites. EcoDataCenter broke ground at the former Kvarnsveden mill in Borlänge, Sweden, in September 2025, and Eclairion is building at a former Arjowiggins mill in Bessé-sur-Braye, France. Sesterce announced a campus at the former Kaipola mill in Jämsä, Finland, in October 2026.
Old industrial land does not set the regions apart, though. 37 of the 295 location entries outside the hubs (13%) describe the site as a former something, against 27 of 173 inside them (16%). The tracker does not record whether an old site’s grid connection will be reused. A siting team would put that question to the grid operator first.
Worked example: reading Finland
Take Finland, the largest single market, and read it as a siting team would. It has 41 tracked projects: 15 announced, 10 in planning, 8 permitted, and 8 under construction or structurally complete. Physical work is on record only for that last group.
Then the grid. Fingrid, the Finnish transmission operator, accepts an application for a connection agreement only when a project has a legally effective zoning plan and a legally effective building permit. Fingrid also says connection capacity is temporarily scarce in some regions. The tracker shows no permit yet for the 25 Finnish projects that are announced or in planning, so under that rule none of them can apply for a connection agreement yet.
One caution. Finland’s lead partly reflects our own research: 35 of its 41 rows were added on 11 October 2026, when we went through Finland in depth. The Finland page lists them with their sources.
Check your own market in two minutes
- Open the pipeline tracker and pick a country. Each country opens its market page, with projects by stage.
- Read the stage before the count. An announced project has a published plan, and no permit or start of works that we could find.
- Look at the milestone date. The tracker page flags how many projects have had no public milestone for 18 months or more, and an old date deserves a second look.
- Then open the grid connection tracker for the same market: the published wait, the allocation rule and the date we checked each one.
Limits
A count of tracked projects is neither a census nor a measure of capacity. The tracker covers projects of 5 MW or more, or with capacity unpublished, that had a public milestone since January 2024 and are not yet in service. Sources quote capacity as IT load, campus power or grid connection, so the figures cannot be added. Coverage is uneven. Research rounds in October 2026 went deeper in some markets: Frankfurt, Amsterdam, Milan and Dublin among the hubs, and Finland outside them. Two projects, in France and Greece, are counted at their last stage although a public setback has put them in doubt. All counts are as of 15 October 2026.
Cite this: ScienceShot, Where is Europe building data centres outside the big hubs?, October 2026, scienceshot.com, scienceshot.com/post/data-centres-outside-big-hubs-europe.
Cite this article
Turner, A. (2026, October 23). Where is Europe building data centres outside the big hubs? ScienceShot. https://scienceshot.com/post/data-centres-outside-big-hubs-europe
Turner, Alex. “Where is Europe building data centres outside the big hubs?” ScienceShot, 23 Oct. 2026, scienceshot.com/post/data-centres-outside-big-hubs-europe.
Turner, Alex. “Where is Europe building data centres outside the big hubs?” ScienceShot, October 23, 2026. https://scienceshot.com/post/data-centres-outside-big-hubs-europe.
@online{scienceshot-data-centres-outside-big-2026,
  author       = {Turner, Alex},
  title        = {{Where is Europe building data centres outside the big hubs?}},
  organization = {ScienceShot},
  date         = {2026-10-23},
  year         = {2026},
  url          = {https://scienceshot.com/post/data-centres-outside-big-hubs-europe}
}
https://scienceshot.com/post/data-centres-outside-big-hubs-europe
Get the weekly brief
Sourced analysis of data-centre engineering and regulation, every Monday. No spam, unsubscribe any time.